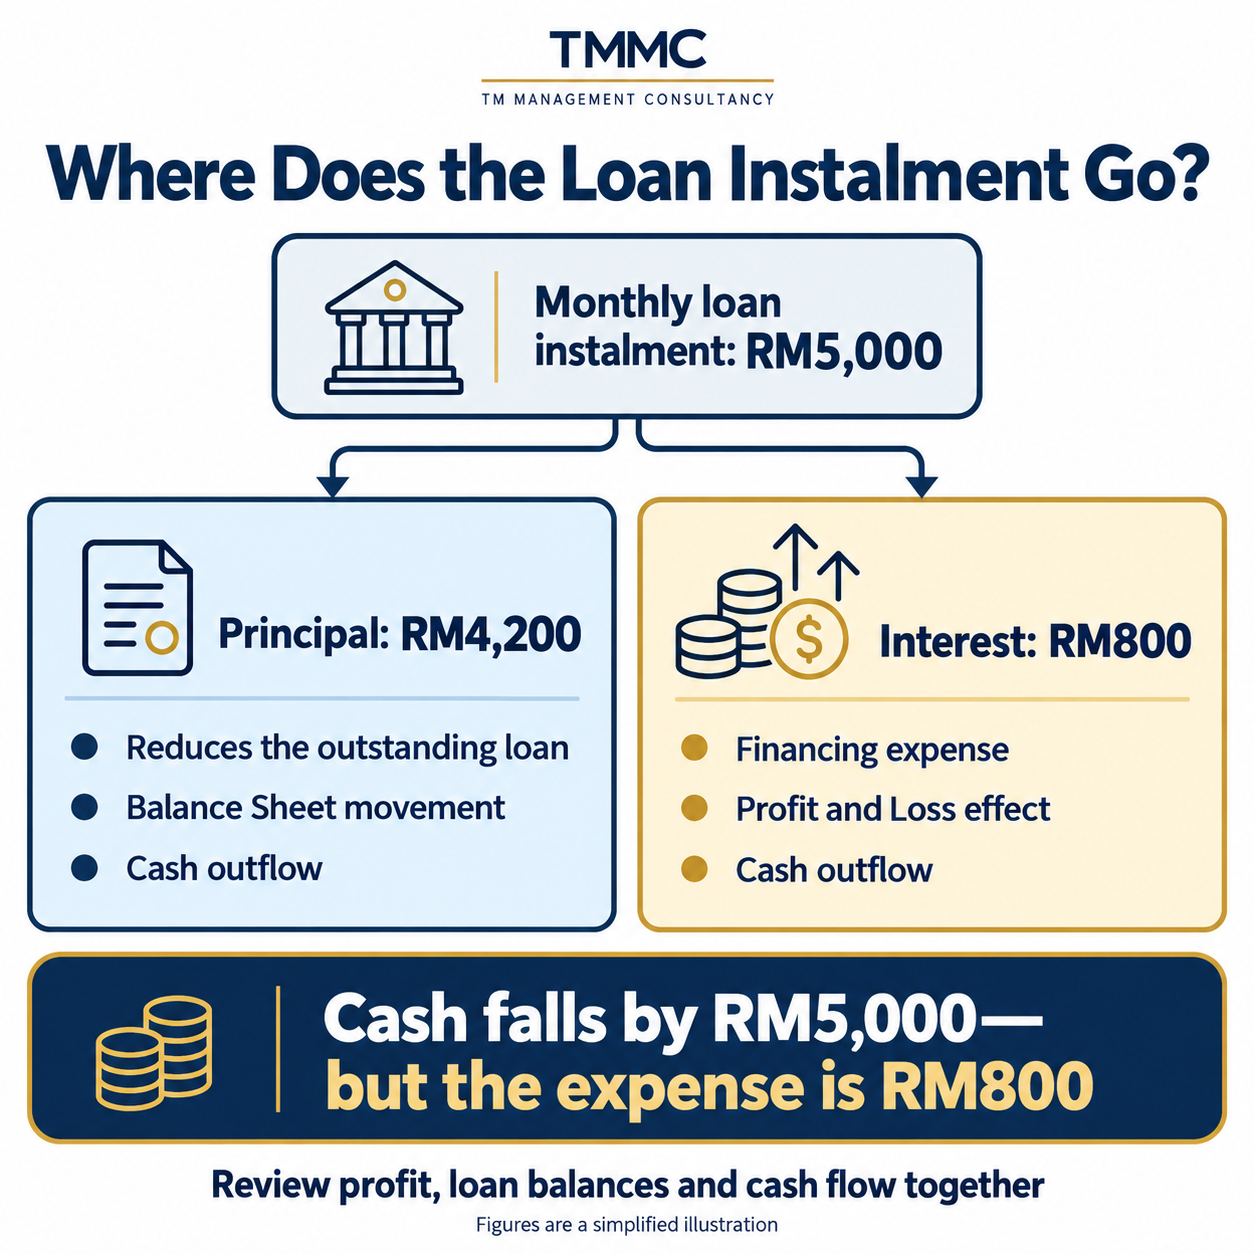
A Loan Instalment Reduces Cash In Full—But Only The Interest Portion Is A Financing Expense.
Consider a simplified monthly loan instalment of RM5,000:
- Principal: RM4,200 reduces the outstanding loan on the Balance Sheet and reduces cash.
- Interest: RM800 is a financing expense in the Profit and Loss Account and reduces cash.
Cash therefore falls by RM5,000, while the expense recorded for this instalment is RM800. The RM4,200 principal repayment is not an expense; it reduces the loan liability.
This distinction matters when reviewing profit and cash flow. A business may report a profit but still experience cash pressure because principal repayments use cash without reducing profit.
The actual split between principal and interest may change over the loan term. Use the lender’s repayment schedule and reconcile the loan balance regularly.
Review profit, loan balances and cash flow together.